Ohio Minority Supplier Development Council

Built for This: How Mekka Don Channeled a Lifetime of Branding Into ELLIFLY

Jamie R. Van Doren

Mekka Don has spent much of his career thinking about brands.

First, he helped protect them.

A law school graduate who began his career in intellectual property law, Mekka worked with businesses and organizations to safeguard the ideas, identities and assets they had built. Then he found himself on the other side of the equation, building a brand of his own.

As an entertainer and artist, Mekka learned firsthand what it meant to compete for attention. He learned how to position himself, tell a story and remain visible in a crowded marketplace. Later, while living in New York, he began applying those lessons to clients, including athletes and celebrities, through branding, marketing, positioning and legal consulting.

Those might look like several different careers.

Mekka sees them differently.

“I do believe that everything that I’ve done in my life has brought me to this exact moment, this exact business,” he said.

That business is ELLIFLY, an AI-powered brand platform Mekka launched to help businesses solve a deceptively difficult problem: showing up consistently in a world where visibility increasingly matters.

But the idea for ELLIFLY started with a problem Mekka saw in his own work.

Advice Wasn’t Enough

As a consultant, Mekka could help clients understand their brands. He could identify opportunities, recommend positioning and offer ideas for reaching their audiences.

Then he began noticing a gap.

“I realized that a lot of the things that I was telling people as a consultant, a lot of the ideas that I was giving, a lot of the directives…were great,” he said. “But I didn’t offer anybody a true system that I think that they could take those things and go implement them with.” It was an important distinction.

Knowing what to do and having the capacity to do it aren’t the same thing. For a small business owner, consistent marketing can mean finding ideas, writing posts, creating content, scheduling it and managing multiple channels, all while running the actual business. Hiring someone else to do it can solve the problem, but often at a price smaller companies can’t afford.

Mekka knew the problem personally. Even with his background in branding and marketing, managing his own social media consistently demanded time and attention.

Around the same period, several pieces began coming together.

A scholarship took him to Dartmouth for an executive education program, where conversations with entrepreneurs, businesses and professors pushed him to think differently about his own offering. At the same time, generative AI was rapidly expanding what small teams and individual entrepreneurs could build.

The opportunity became difficult to ignore.

An Ohio Homecoming

ELLIFLY may be a technology company, but its roots are also firmly planted in Ohio.

Mekka had built much of his professional career in New York. Then the pandemic arrived at an unusually complicated moment. He was recovering from foot surgery, navigating New York on a knee scooter and raising a two-year-old son.

He and his wife began reconsidering where they wanted to build their lives.

Columbus stood out.

The city Mekka remembered from high school and college had changed. He saw growth, business development and new opportunity, along with relationships he had built in Ohio over many years.

Coming back, he says, was “one of the best decisions I’ve ever made.”

It also put him in Columbus as another transformation was beginning, this one driven by artificial intelligence.

“It’s Now or Never”

Mekka’s interest in AI goes beyond using a new technology to make marketing easier.

He sees AI as part of a much larger economic shift, one with the potential to create significant new wealth. And history, he argues, offers reason to pay attention to who gets to participate in creating that wealth.

“People who look like us generally are not on the building side of those things when they happen,” he said.

This time, he saw an opening.

Generative AI has lowered some of the barriers that once made building a technology company extraordinarily expensive. Products that might once have required large development teams and significant upfront capital can increasingly be built and tested by much smaller teams.

For Mekka, that changed the equation.

“I was like, no, I have to go,” he recalled. “It’s now or never.”

That doesn’t mean he’s uncritical of the technology. Mekka is candid that no one knows exactly where AI is headed, and he believes questions about responsible use are legitimate.

But waiting for certainty carries its own risk.

For businesses, he believes some level of AI proficiency will increasingly become part of what it means to remain competitive. The immediate opportunity isn’t necessarily replacing people. It’s using technology to reduce repetitive work, improve efficiency and give people more time for the work where their judgment and expertise matter most.

“Even just from a practical day-to-day side, we don’t have a choice really to just say, ‘Oh, we’re just going to ignore this thing and we’re just going to keep operating the way we’ve operated before,’” he said.

ELLIFLY is Mekka’s attempt to put that philosophy into practice.

Turning a Brand Into a System

At its core, ELLIFLY is designed around a challenge familiar to almost every small business: maintaining visibility without allowing marketing to consume the time needed to run the company.

The platform starts by learning the business itself. Who’s the target audience? What differentiates the company? How does it communicate? What should its brand sound like?

From there, businesses can generate content ideas and create social posts, newsletters, blogs and emails in a voice aligned with their brand. The platform also includes an asset library, scheduling and automated posting capabilities, with additional functionality continuing to develop.

Mekka originally thought of ELLIFLY as a brand-alignment platform.

Increasingly, he describes it as a “brand operating system.”

The distinction matters because the goal isn’t simply to generate more content. It’s to create a repeatable system for something many businesses approach sporadically.

For Mekka, visibility isn’t about winning a popularity contest. It’s become part of how customers decide which companies they recognize and determine whom they trust.

From an Idea to Traction

ELLIFLY is still a young company, but the business has begun generating signs of momentum.

Mekka won the pitch competition at Black Tech Week and has spoken about his work at Black Tech Week and Harvard. ELLIFLY has recently hired two employees, something Mekka points to with particular pride because company growth is beginning to translate into job creation.

The company has also signed two Division I athletes as ambassadors and is working to add more. That strategy connects back to Mekka’s experience in sports and his belief that young people should begin thinking about their brands and professional positioning well before they enter the job market.

Partnerships represent another piece of the growth strategy.

Organizations serving entrepreneurs and small businesses regularly hear requests for help with branding and marketing. But most weren’t designed to become marketing agencies for the businesses they serve.

Mekka sees an opportunity for ELLIFLY to fill part of that gap.

OMSDC is among the organizations partnering with ELLIFLY, and Mekka says conversations are underway with other organizations around the country. Rather than asking those organizations to reinvent what they already do well, his goal is to give them another tool to help businesses put good advice into practice.

For Ohio businesses, that partnership also comes with a tangible benefit: businesses that sign up for ELLIFLY through OMSDC receive 15% off their subscription price.

The Importance of Visibility

Mekka doesn’t have to look far for evidence that visibility matters. His own career provides it.

“I get called all the time for different things that I don’t know how people found me,” he said. “They say, ‘Oh, I saw you on the Internet.’”

There isn’t one post he can point to, or one campaign that made it happen. It’s the accumulated effect of years spent building a recognizable brand and consistently putting his work out into the world.

For small businesses, Mekka believes that kind of visibility has become a business imperative. Customers discover companies online. They form impressions before ever making contact. And increasingly, the businesses that remain visible and relevant have an advantage over equally capable competitors that don’t.

What has changed is the cost of doing it.

A generation ago, reaching an audience at scale often meant paying for access through television, radio or print. Social media has dismantled much of that barrier. Now AI is lowering another one by making some of the work required to maintain a consistent presence faster and more affordable.

That opportunity is at the heart of ELLIFLY. But it also reflects something larger about Mekka’s own journey.

The lawyer learned how to protect a brand. The entertainer learned how to build one. The consultant saw how difficult it was for businesses to turn good advice into consistent execution. Then a new technology arrived that gave him the chance to bring those experiences together in a way that hadn’t been possible before.

He could have watched that opportunity develop from the sidelines.

Instead, he decided it was “now or never.”

For Mekka, building ELLIFLY isn’t a departure from everything that came before.

It may be what all of it was preparing him to do.

Explore ELLIFLY and save 15% through OMSDC:
https://ellifly.com/OMSDC/

Trend Watch: The Next Energy Constraint Isn’t Supply. It’s Delivery.

The largest buildout in a generation is stalling at the connection point. That’s where the supplier opportunity is

Jamie R. Van Doren

This is the second in a three-part Trend Watch series on what’s actually changing in energy. Part one covered the largest power customers in the country walking away from the utility model. This installment covers what stopped them anyway.

On August 3, the governor of Texas told the data center industry to stop.

Less than a year after branding his state the epicenter of AI development, Greg Abbott ordered a halt to data center approvals. No new connections to the Texas grid until the Public Utility Commission of Texas and ERCOT audit what’s already sitting in the queue. Developers now have to disclose the tax breaks they’re receiving, how much power they’ll draw and generate, how much water they’ll use and how they’ll cool the facility, what they’re doing to limit the effect on the people who live nearby, and who actually owns the building.

His instruction to regulators wasn’t subtle. Any project that fails the process has to be denied.

The number behind the order explains it. ERCOT’s interconnection queue holds roughly 474 gigawatts of requests. That’s more than five times the state’s all-time record peak demand. Around 90 percent of it is data centers.

Texas wasn’t even first. New York paused approvals for large data centers in July, for up to a year, while it writes new rules. ERCOT has already postponed the first round of classification notices under its new large-load process and goes back to state regulators on August 20 for more time.

They Solved Supply. It Didn’t Help.

Last month we covered the largest power consumers in the country deciding they could no longer wait for the grid. Microsoft restarting Three Mile Island. Meta buying the entire output of an Illinois nuclear plant. They looked at utility timelines, decided the math didn’t work, and went and bought the megawatts themselves.

It worked, on paper. Meta’s Illinois output starts in 2027. Three Mile Island targets 2028.

Those are contracts, not electrons. The buildings meant to use that power still have to be permitted, connected, cooled, and backed up. Some of them can’t be.

That’s the constraint hiding inside the energy conversation, and it isn’t generation. It’s delivery. Getting electricity from where it’s made to where it’s needed, through equipment that exists, into a building that can shed the heat, backed by something that turns on when the grid can’t.

Each of those is a separate point of failure. Each of them is somebody’s contract.

The Wall Is Made of Equipment and Permission

Start with the hardware. GE Vernova closed the second quarter with 116 gigawatts of gas turbine orders and slot reservations, up from 100 three months earlier, and is now booking 2031 delivery slots. Siemens and Mitsubishi are four to five years out too. That isn’t a shortage of demand, capital, or willingness to build. There’s a shortage of the physical objects that move and convert electricity, and of the factories that make them.

Then permission. Interconnection studies, transmission planning, environmental review, local zoning. A transmission line in this country still takes ten to fifteen years to permit and build. The Texas order didn’t create that friction. It formalized it.

Then heat. A gigawatt-scale computing facility is, in engineering terms, a very large space heater with a business model attached. It’s a determining constraint on where the project can go at all, which is why water use showed up in a grid reliability order.

And then behavior. Grid planners historically treated large industrial loads as steady and predictable. AI compute isn’t.

On July 10, 2024, a lightning arrestor failed on a 230 kV line in northern Virginia. Auto-reclose settings turned that into six faults in 82 seconds, and roughly 1,500 megawatts of data center load came off the system at once. Those facilities are built to protect themselves from voltage disturbances. NERC formed a task force.

Three weeks ago it happened again at double the scale. On July 22, a line fault in Ashburn pushed more than three gigawatts onto backup power, about three percent of PJM’s demand. Dominion was clear it hadn’t shed those customers. Their own protection systems did. The disturbance registered as far west as Chicago.

Nothing was short of power. The load moved faster than the system could respond, because equipment inside private buildings decided it should.

The Grid Is Already Borrowing From Private Buildings

In May, the Department of Energy issued an emergency order under Section 202(c) of the Federal Power Act authorizing PJM to deploy backup generation resources at data centers and other major facilities across the Mid-Atlantic. In late July, a comparable order covering the Southwest Power Pool allowed operators to call up idle backup generation across 17 states, in territory home to about 20 million people. In early July, PJM issued the first emergency backup-generator warning in its history.

These orders usually get read as a story about how close the grid is running to the edge. That’s true. It’s also not the most useful part.

The useful part is where that reserve capacity actually lives. It lives in private buildings. It’s the generator set behind a data center, the switchgear in a hospital basement, the controls package that decides what happens in the four seconds after utility power drops. Federal reliability policy now quietly assumes all of that equipment exists, works, has fuel, and answers when called.


Somebody specified that equipment. Somebody installed it, integrated the controls, negotiated the fuel contract, ran the load bank test, and shows up when it fails. Those are supplier relationships, and the reliability of the American grid is now leaning on them.

Ohio Is Already Paying For This

None of this is happening somewhere else. Ohio sits inside PJM, the grid operator covering thirteen states, and PJM’s capacity market is the clearest scoreboard we have for whether delivery is keeping up.

It isn’t. PJM has now missed its own reliability requirement in two consecutive capacity auctions, the first time in its history the entire region has come up short. July’s auction fell 6,831 megawatts short and cleared at the federally approved cap of $325 per megawatt-day, for $16.4 billion. PJM says it will ask federal regulators in September for a special backstop procurement. In the prior auction, nearly 5,100 megawatts of the increase in forecast peak load came from data centers.

Closer to home, the numbers are contested. Regulators approved an increase to AEP Ohio’s transmission rider in March that added about $7.90 a month for a typical household, though offsetting decreases elsewhere on the bill left the average net change closer to twenty cents. Under AEP Ohio’s large-load tariff, data centers must pay for at least 85 percent of the capacity they reserve whether they use it or not. The Ohio Manufacturers’ Association has appealed that tariff to the Ohio Supreme Court, and a bill in the legislature would extend it statewide.

If you operate a facility in Ohio, this is already in your budget. If you sell to companies that operate facilities in Ohio, this is already in theirs.

Delivery Is a Procurement Category

This is the part most people miss.

You don’t have to generate electricity to sell into the energy buildout. The work is in everything that stands between a megawatt and a running operation.

Electrical contracting at industrial scale. Substation and switchgear work. Mechanical, HVAC, and thermal management. Water treatment and cooling systems. Civil and site construction. Controls, instrumentation, and automation. Backup generation, load bank testing, and commissioning. Fuel supply and emergency logistics. Operational technology cybersecurity, a different discipline from IT security. Environmental and permitting consulting. Ongoing operations and maintenance.

Some of that work has already started. In Virginia, owners are retuning facility control systems so sites ride through brief faults instead of dropping offline, and federal regulators have told NERC to write mandatory standards for large computing loads by year end. All of it has to be engineered, installed, tested, and documented, site by site.

For an MBE, the question isn’t “Are we an energy company?” Almost none of these firms are. The question is “Do we work on the systems that make power usable?” For a surprising number of businesses in our network, the honest answer is yes, and has been for years, in buildings nobody called an energy project.

The New Rules Are Also a New Opening

Look again at what Texas is asking developers to submit. Tax breaks. Power use and generation. Water use and cooling. Efforts to reduce the impact on nearby residents. Facility ownership.

Three of those are engineering questions. Two aren’t.

Community impact and ownership disclosure are social license questions, and they just landed inside a grid connection application. That happened because the politics moved. On July 18, a group called HumansFirst coordinated 142 protests across 42 states against the data center buildout. A June Reuters/Ipsos poll found only about a third of Americans approve of the current pace of construction, and just 14 percent would want a facility in their own community.

For a buyer assembling a project team under that kind of scrutiny, a supplier base that’s local, certified, documented, and visibly connected to the community stops being a values statement and starts being part of the filing.

No regulator has said anything about supplier inclusion. But when reviewers start asking who benefits from a project and who owns it, the answers get easier for buyers who can point to real local firms doing real scopes of work. That’s a case OMSDC’s members are unusually well positioned to help make, and almost nobody is framing it that way yet.

What To Do About It

For MBEs:

Rewrite your capability statement in the language of this market. Not “general contracting” but substation civil work. Not “IT services” but OT security assessment for industrial control systems. Buyers in this sector search for specific scopes, and generic language reads as no experience. Then get clear about which scopes you can carry alone and which require teaming. The pursuit pod model from our Growth Under Pressure white paper applies directly. One firm rarely covers a delivery scope. Three often can.

For corporate members:

Your supplier bench is about to be tested by demand you probably didn’t forecast. Waiting for a formal RFP means competing for what’s left. Start the qualification conversations before the constraint becomes an emergency, and look hard at the maintenance, backup, and commissioning categories. Those are the ones that quietly determine whether your operation stays up the next time a fault ripples through the system.

The Takeaway

For a century, the hard question in energy was how to make more of it. That question got solved. What they found on the other side was a second wall, built out of transformers, permits, cooling towers, interconnection queues, and public patience.

The next decade of energy work isn’t going to be dominated by the companies that produce power. It’s going to be dominated by the ones that deliver it, cool it, back it up, secure it, and keep it running when the margin gets thin.

That’s not an energy industry. That’s a construction, trades, engineering, logistics, and services industry, and it’s the one our members are already in.

Next month we close the series with what gets built next, and with a company right here in Ohio that’s already building it.

Until then, the question to sit with is this. If the biggest buyers in the country can own the power and still not be able to use it, who do you think they’re going to call?

Use AI to Get Clear. Then Get Heard.

by Jamie R. Van Doren

AI has made it remarkably easy to create marketing content. Give ChatGPT, Claude, Gemini or any number of other tools a topic and, within seconds, you can have a LinkedIn post, an email campaign, website copy or a month of social media ideas.

The problem is that your competitors can do exactly the same thing. As the cost of creating content approaches zero, simply producing more of it becomes less of an advantage. In fact, the businesses that benefit most from AI may be the ones that spend a little less time asking it to write and a little more time using it to think.

Because before AI can help communicate your brand, you have to be clear about what that brand actually represents. You may be capable. You may be qualified. You may deliver excellent work. But if a potential customer can’t quickly understand your value, you can still be overlooked. Clarity helps people understand you faster, trust you sooner and remember you longer.

Start With What You Want to Be Known For

A logo identifies your business. Marketing communicates what you do and why. Your brand is the expectation people attach to your name. That expectation is built over time through experience, reputation, trust, consistency, proof and personality. And while you can influence it, ultimately it lives in the minds of your customers.

One useful exercise is to imagine that you aren’t in the room. Could one of your customers clearly explain who you serve, what problem you solve, how you’re different and why any of that matters? Could your employees?

Those four questions expose a surprising amount. Many business owners can explain what they do. Fewer can explain why a particular customer should choose them.

The problem often starts with how companies describe themselves. Visit enough websites and you’ll encounter the same vocabulary: innovative, world-class, best-in-class, scalable, cutting-edge, seamless. The words sound impressive until everyone uses them. The result is a kind of corporate camouflage.

If five qualified companies all describe themselves in essentially the same language, the buyer is left searching for another basis on which to choose. Often, that means price.

A stronger value proposition starts with greater specificity. Who are you particularly well suited to serve? What problem do you solve for them? What changes because you solved it? What makes your approach meaningfully different? And what evidence supports that claim? Those are business questions before they’re marketing questions. And they’re an excellent place to use AI.

Use AI as an Interviewer

One of the most useful ways to work with AI is also one of the simplest: stop trying to give it all the answers. Ask it to interview you.

For example:

“Ask me one question at a time to clarify my value proposition: who we serve, the problems we solve, the outcomes, our differentiators and the proof. Don’t draft until we agree on the elements of the value proposition.”

That changes the nature of the exercise. Instead of staring at a blank page trying to manufacture the perfect positioning statement, you’re responding to questions about a business you already understand. AI can push for specificity, identify gaps, notice patterns across your answers and help organize the thinking.

The quality of the process still depends on your judgment. If AI suggests that something is a differentiator and every competitor makes the same claim, challenge it. If it describes a customer priority you haven’t validated, question it. If it produces a claim you can’t substantiate, remove it.

The value isn’t that the machine knows your business better than you do. It’s that a good series of questions can help surface knowledge you’ve never taken the time to articulate.

Give AI a Memory

Once you’ve done that work, capture it. A useful brand guide doesn’t have to be a 50-page document produced by an agency. For many businesses, a few well-developed pages covering audiences, customer problems, value proposition, differentiators, proof, personality, voice, key messages and language to avoid can dramatically improve consistency.

More importantly, that document can become a reusable source of truth for your AI tools. Instead of beginning every conversation by explaining who your company is, you can give the system the context once and use it repeatedly. Depending on the platform, that might mean project knowledge, uploaded reference documents or another persistent workspace.

This solves one of the most frustrating problems with AI-generated marketing: every new conversation feels like hiring a new employee who hasn’t attended orientation. Your brand guidelines become the orientation.

They also create discipline inside the company. If your website says one thing, your capability statement says another and your sales team describes the company a third way, AI can help surface those inconsistencies. But first, there has to be an agreed-upon reference point.

Stop Prompting With Topics

Once the foundation exists, content creation becomes much easier. “Write a LinkedIn post about my company” gives an AI system almost nothing useful to work with. It has to guess who you’re speaking to, what you’re trying to accomplish, what distinguishes you, how you sound and what evidence it can use. Those guesses are where generic content comes from.

A better request includes the audience, purpose, value proposition, voice, proof point, call to action and even words or phrases you don’t want used. The improvement isn’t really about learning to write elaborate prompts. It’s about having better inputs.

And those inputs become reusable. A single insight about a customer problem can become a LinkedIn post, an email newsletter, a short video or a presentation. The format changes while the underlying message remains consistent.

That distinction matters because consistency doesn’t mean repeating the same post. It means reinforcing the reputation you want to build from different angles: customer problems, completed work, expertise, process, lessons learned, outcomes, industry changes and community relationships.

Clarity Becomes More Valuable as Content Gets Cheaper

We’re entering a period in which almost every business will have access to tools capable of producing competent marketing content at enormous scale. That doesn’t mean every business will communicate well. If anything, an abundance of content makes it easier for companies that sound alike to disappear into the noise.

The advantage belongs to businesses that know who they serve, understand the problems they solve, can explain why they’re different and have evidence to support it. AI can then help carry those decisions across more channels, more consistently and with far less effort.

That’s a much more interesting use of the technology than simply asking it to write another post. Before you ask AI to help more people hear you, use it to get clearer about what you want them to hear.

Trend Watch: The Biggest Energy Customers Aren’t Waiting for the Grid Anymore

Why the private energy buildout is creating a supplier opportunity that everyone else is missing.

This is the first in a three-part Trend Watch series on what’s actually changing in energy, beyond the daily headlines about policy fights and AI demand. The argument across these three pieces: the energy economy is being rebuilt from the ground up. I believe the supplier opportunity is bigger than anyone is talking about.

What Changed?

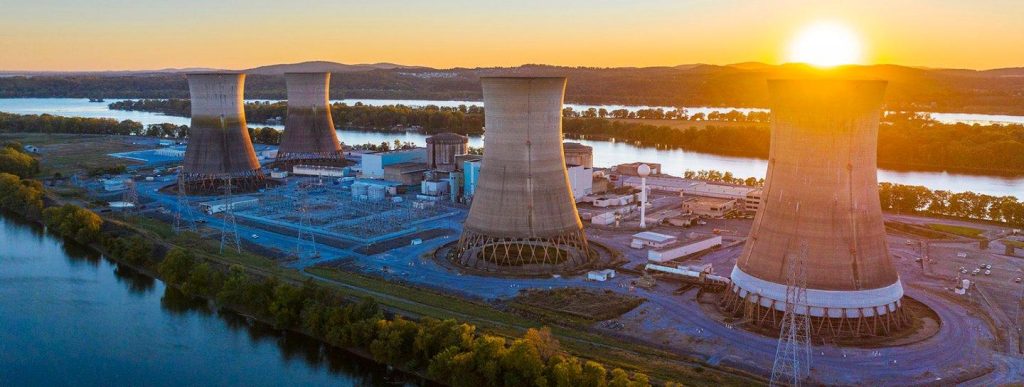
In September 2024, Microsoft signed a 20-year power purchase agreement with Constellation Energy to restart Unit 1 of Three Mile Island. Yes, that Three Mile Island. The plant had been shut down since 2019, mothballed after it couldn’t compete with cheaper natural gas. Now, Constellation will spend $1.6 billion to bring it back online, targeting 2028. The facility has been renamed the Crane Clean Energy Center. Every megawatt it generates, all 835 of them, will go to one company – Microsoft.

This is not how the energy business is supposed to work.

For roughly a century, the model was simple. Utilities built power plants. Customers, including very large ones, bought electricity from those utilities at regulated rates. Even the biggest industrial users were, fundamentally, retail buyers. They negotiated terms. They didn’t commission their own reactors.

But that model is breaking. In any other timeline, the Microsoft deal would be considered an outlier. It’s quietly becoming the new template.

In 2025, Amazon Web Services signed a 17-year agreement with Talen Energy to take 1.92 gigawatts directly from the Susquehanna nuclear plant in Pennsylvania. Google signed a fleet agreement with Kairos Power to deploy small modular reactors by 2030, alongside separate geothermal deals with Fervo Energy. Amazon has invested $500 million in small modular reactor development of its own. Meta signed a 20-year deal with Constellation for the entire output of the Clinton Clean Energy Center in Illinois — 1.1 gigawatts beginning in June 2027. And Meta has also disclosed an even larger 6.6 gigawatt nuclear procurement strategy to support its “Prometheus” AI data center project. For context, that’s more electricity than the peak demand of the city of Chicago. Going to one company. For one project.

Stack those announcements together and you can see the pattern. The largest power consumers in the country are no longer waiting for utilities to build what they need. They’re commissioning their own infrastructure, signing private agreements with generators, and in some cases buying entire plants. They’re exiting the consumer side of the utility model and building their own energy fiefdoms instead.

That shift is the single most important thing happening in American energy right now. And almost no one is framing it that way.

Why Does It Matter?

Most of the mainstream energy conversation is, understandably, still focused on supply and demand. How much power will the grid need? Where will it come from? Can renewables scale fast enough? Will gas plants get permitted? Those questions matter. They’re also a generation behind the actual story.

The actual story is more profound, with much bigger implications for all of us. So, what happens when the biggest customers stop relying on the utility companies? Three things.

First, the financing model changes. A traditional utility raises capital based on regulated returns and recovers costs through rate base over decades. A hyperscaler buying a nuclear plant is doing a different kind of math. They have the balance sheet to underwrite the entire project against their own consumption. That makes some projects pencil out that wouldn’t have otherwise. It also concentrates risk in a way the system hasn’t ever had to plan for.

Second, the procurement model changes. When Microsoft signs a 20-year power purchase agreement, they’re not just buying electrons. They’re buying all the infrastructure and any new capacity. They also have a direct stake in site selection, permitting timelines, construction quality, fuel logistics, cybersecurity, and the ongoing operations. Decisions that used to live inside a regulated utility, that were invisible to most, now live inside a procurement function at a tech company. This is the upside, the potential payout, for companies nimble enough and in-the-know. Those procurement teams are sourcing differently, and they’re sourcing fast.

Third, the supplier model changes. This is the part that matters most for OMSDC’s community. And it’s the part the trade press has barely started to cover. A century-old utility has an established supplier bench. They’ve worked with the same engineering firms, the same EPC contractors, the same equipment vendors, for decades. It’s difficult for someone new to get a toe in the door. But when a tech company decides to build its own energy infrastructure, that bench doesn’t transfer automatically. The supplier ecosystem has to be rebuilt for a new kind of customer, with new requirements, on a new (faster) timeline.

That’s the opening. That’s your foot in the door.

The Supplier Ecosystem Most People Haven’t Mapped

When a hyperscaler commits to a multi-billion-dollar energy project, they need more than a generator. They’re doing an entire buildout. Each layer of that buildout is a supplier opportunity, and most of them are categories where our minority-owned businesses already have real capability.

Site selection and acquisition. Permitting and regulatory work. Civil and structural construction. Heavy electrical contracting at industrial scale. Mechanical, HVAC, and cooling systems. Controls and automation. Fuel and logistics for backup and bridging power. Cybersecurity for operational technology (which is a different discipline from IT security). Workforce. Ongoing operations and maintenance. Site security. Environmental compliance. Communications infrastructure.

Each of these is a category. Each category is hiring. And because the projects are moving faster than typical utility timelines, the supplier benches are forming right now. Not in 2030.

There’s a simple test for whether a market is still open. Ask whether the major buyers have settled on their preferred suppliers yet. For hyperscaler energy projects, the answer is likely, mostly no. Microsoft, Amazon, Meta, and Google are all building these supplier relationships in real time, right now. The companies that get in the door now are establishing track records that will matter for the next 20 years of buildout. OMSDC and NMSDC need to be at the forefront of helping to knock on those doors.

Because the companies that wait until the RFPs are published are likely to be competing for second-tier work after the primary benches are locked in.

Why This Is Happening Now

It’s worth understanding why this shift is occurring, because the explanation tells you whether this is a moment or a movement.

The short answer is that the utility model simply cannot deliver what the largest customers need on the timelines they require. Not anymore. Especially with our ageing infrastructure and lack of investment in that infrastructure.

A new transmission line in the United States takes 10 to 15 years to permit and build. Connecting a new data center to the grid in many markets takes three to seven years. The largest hyperscalers are planning capacity expansions on 18 to 36 month cycles, driven by AI training and inference demand that didn’t even exist five years ago. Waiting for the grid to catch up is not an option. The perceived economics of being late to AI are orders of magnitude larger than the cost of building your own power.

Add to that the carbon commitments these companies have made. Microsoft has pledged to be carbon negative by 2030. Google and Amazon have similar targets. Buying generic grid power, which still includes substantial fossil generation in most regions, doesn’t get them to those goals. Signing direct deals for nuclear, geothermal, or behind-the-meter renewable generation does. While the current Administration has been anti-Green, the carbon commitment is still a policy lever. The infrastructure deal is how these companies can execute on their commitment.

Finally, regulatory uncertainty is pushing in the same direction. With the current federal posture pulling back on parts of the clean energy agenda, hyperscalers cannot count on policy to deliver the energy mix they’ve committed to. So they’re building it themselves.

None of these forces are temporary. The economics of AI compute, the carbon commitments, and the regulatory volatility are all multi-decade phenomena. This is a movement, not a moment.

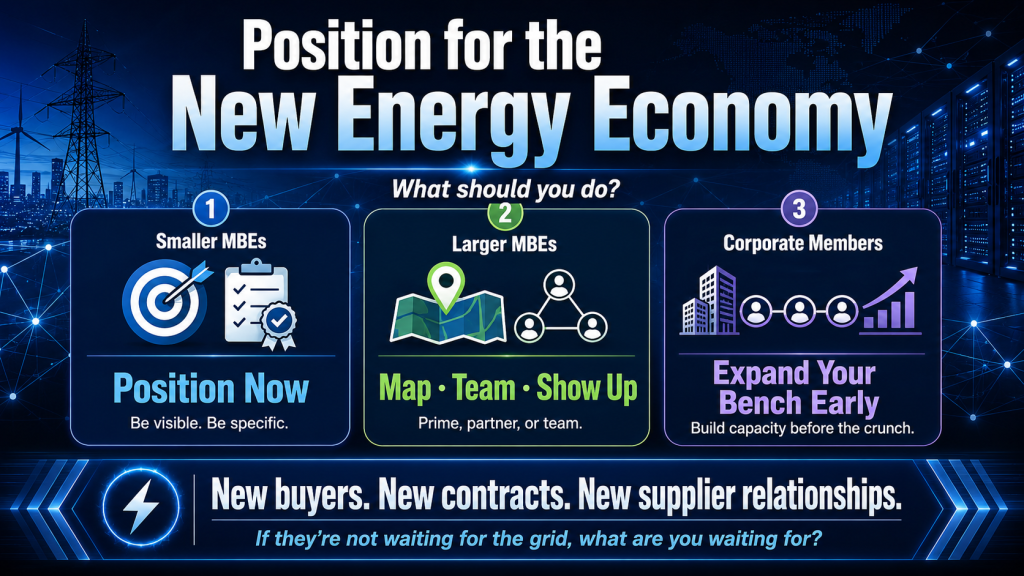
What Should You Do?

For smaller MBEs:

If your business touches any part of the energy buildout, even tangentially, this is the year to position. That includes electrical contracting, HVAC and mechanical work, civil construction, trucking and fuel logistics, security services, environmental consulting, IT and OT cybersecurity, facilities maintenance, and specialty trades. Get your certifications current. Get your capability statement specific to the energy and data center sector, even if most of your work has been in other industries.

The biggest mistake here would be assuming you need to be an “energy company” to participate. You don’t. The hyperscalers are buying the same services any large industrial project would need, from suppliers who can deliver on infrastructure timelines.

For larger MBEs:

Map your capabilities against the supplier categories above and identify where you can compete for primary work, where you can compete as a tier-two partner under a larger prime, and where teaming with another MBE would expand your range. The pursuit pod model from our recent Growth Under Pressure white paper applies directly here. A single MBE may not have the breadth to bid a full energy project. Three MBEs together often can.

Also begin the conversations with hyperscaler procurement teams now, before the formal RFP process opens. These companies are sourcing relationally as well as transactionally. The firms that are known, that have shown up, that have documented their capabilities and references in the right way, will be the firms that get called.

For corporate members:

If you operate in or around the energy, manufacturing, or technology sectors, your supplier base is about to be tested by buildout demand you may not have forecast. The same shortage of qualified labor and qualified suppliers that’s driving hyperscaler decisions is going to affect every adjacent industry. Now is the time to expand your supplier bench, not after the constraint becomes a crisis.

For procurement teams specifically: the suppliers who serve hyperscaler projects effectively will become the most sought-after firms in the country over the next decade. Being in those relationships early is a competitive advantage. Being in those relationships through OMSDC’s network is a way to find capable firms before they’re booked.

The Takeaway

For most of the last century, the question of who supplied energy was answered by who held the utility franchise. That question is being reopened. The largest customers in the country have decided they can no longer wait for the grid to deliver what they need, when they need it, in the form they need it.

That decision creates a new energy economy with new buyers, new contracts, and new supplier relationships forming in real time. The companies that recognize what’s happening will help build it. The companies that don’t will read about it in five years and wonder how they missed the opening.

Next month, we’ll cover the constraint that’s becoming a bigger problem than the power itself, and the supplier opportunity hiding inside it.

Until then, the question to sit with is simple. If the biggest energy customers in the country are no longer waiting for the grid, what are you waiting for?

OMSDC Launches AI Learning Hub to Help Members Build Practical AI Skills

AI is moving quickly. For many business leaders, that’s both the opportunity and the anxiety. A webinar can introduce the topic. A workshop can help people try the tools. But real learning usually happens later, when someone sits down to apply the ideas to an actual proposal, a real sales meeting, a competitor they’re losing to, or a decision that can’t wait. That’s why OMSDC has launched the OMSDC AI Learning Hub, a free, self-paced online learning platform for OMSDC-certified MBEs and corporate partners.

The Hub is designed to give members and partners a place to keep learning between sessions. It turns OMSDC’s AI webinar and workshop content into interactive guidebooks that users can read, search, revisit, and apply on their own time, at their own pace. The goal is practical skill-building. Not AI theory for its own sake. And not a one-time presentation that disappears when the meeting ends. The Learning Hub is built to help business leaders use AI in the work they’re already doing: proposals, sales preparation, market research, meeting workflows, marketing, operations, and business strategy.

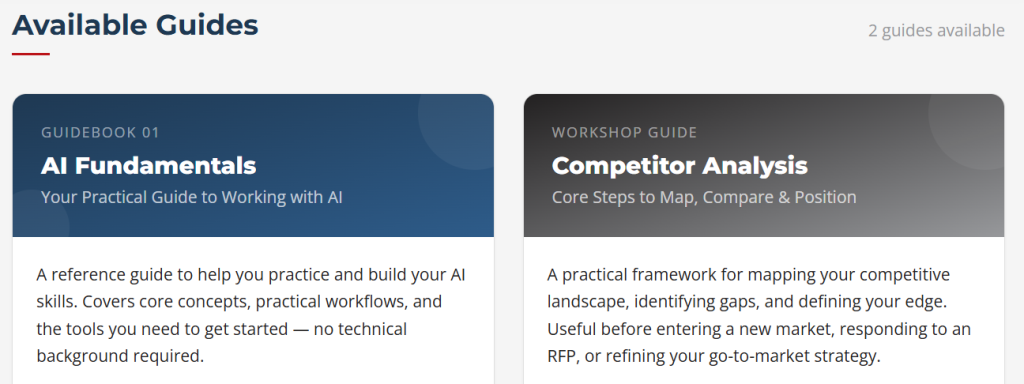
The Hub currently includes two guidebooks: AI Fundamentals and Competitor Analysis.

The AI Fundamentals guide helps users understand what today’s AI tools are, where they can create real leverage, and where caution is still needed. It gives members a stronger foundation for using AI without treating it as magic, surrendering their judgment, or dismissing the real risks.

The Competitor Analysis guide gives users a practical workflow for researching competitors, identifying positioning gaps, preparing for sales conversations, and strengthening strategy. It includes frameworks, prompt templates, exercises, and examples that can be adapted to different industries and business models.

Both guides are designed to be useful after the session ends.

Users can move through the material at their own pace. They can revisit sections when they need a specific framework, search for a particular prompt, or save their progress and pick up where they left off. That matters because most business leaders don’t need more abstract AI content. They need tools they can use when the work is in front of them.

For MBEs, that may mean preparing for a buyer meeting, sharpening a capability statement, researching a new market, improving a proposal, or finding a better way to explain value. For corporate partners, it may mean understanding how AI is changing supplier readiness, internal workflows, market research, communication, and decision support. For both audiences, the larger point is the same: AI skills are becoming business skills.

As OMSDC continues building its AI learning series, the Learning Hub will grow with it—new guidebooks, workflows, session materials, and practical resources added over time. The Hub is best used as a companion to OMSDC’s seminars and workshops. Live sessions create the shared learning experience. The Hub gives members and partners a place to keep applying the material afterward.

OMSDC is also developing an AI 101 course, which will be a self-paced video that users can watch on their own schedule. The course will give members and partners another entry point into the material, especially for those who are newer to AI or want a firmer footing before diving into more advanced sessions. The purpose isn’t to chase every new tool or trend. The purpose is to help OMSDC members and partners build practical AI confidence, one workflow at a time.

AI won’t replace business fundamentals. Companies still need strong relationships, clear value propositions, reliable operations, sound judgment, and the ability to deliver. But AI can help teams move faster, prepare better, communicate more clearly, and compete with more confidence. That’s the role of the OMSDC AI Learning Hub. It gives members and partners a place to learn, return, practice, and build skills they can put to work.

Explore the OMSDC AI Learning Hub